Charles Skorina & Company
● RETAINED EXECUTIVE SEARCH ●
Our clients: visionary families, transformative nonprofits, Wall Street trailblazers
Our vision: build investment preeminence, create opportunity
Our work: recruit, consult, connect
LATEST NEWSLETTER
If you don’t take care of your customer, your competitor will. —Bob Hooey, Make ME Feel Special!
Our fall 2026 Outsourced Chief Investment Officer (OCIO) directory features one hundred-five service providers with names, numbers, and emails for each firm.
Our goal is to give new business prospects – pensions, nonprofits, and family offices – an easy, ad-free, no-paywall, no-charge way to find OCIO firms and connect with the right representative.
Relentless growth
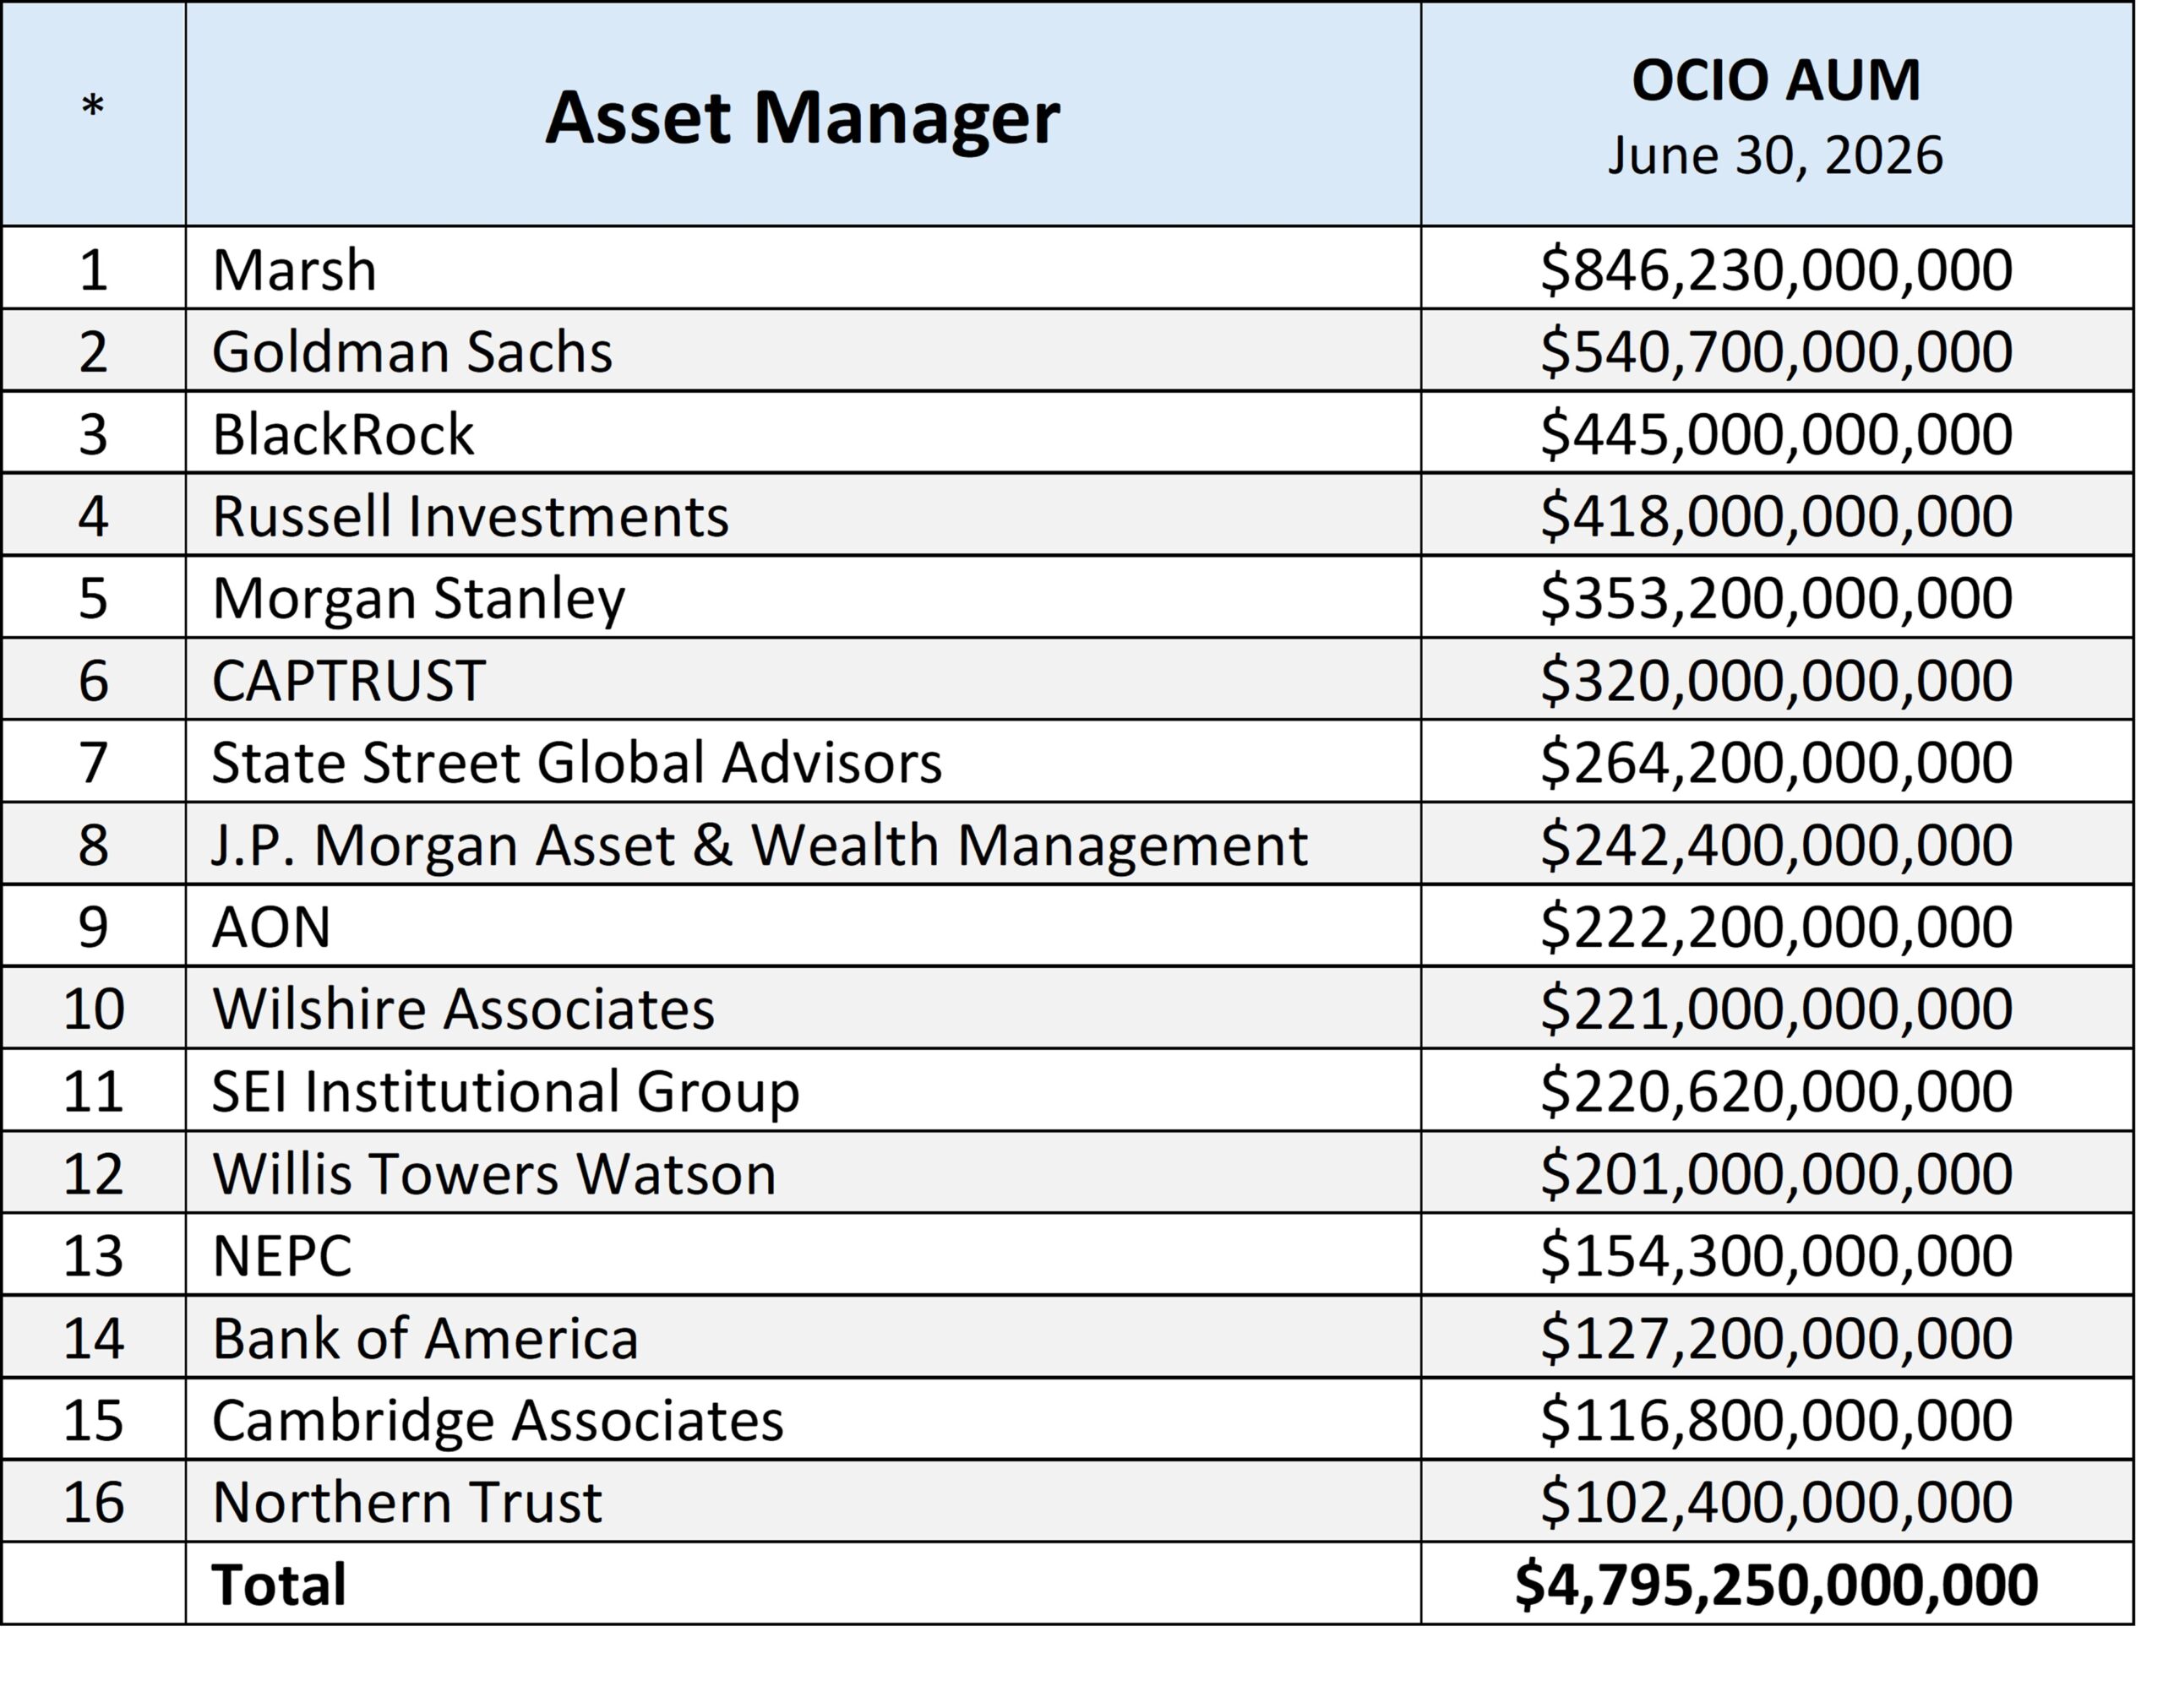
AUM topped $6.3 trillion as of June 30, 2026, an 11.8 percent jump ($666bn) from just six months ago. And, as usual, the big got much bigger. Sixteen firms over one hundred billion manage about seventy-six percent of the assets (mostly pension assets) leaving the remaining trillion-five for independents and boutiques.
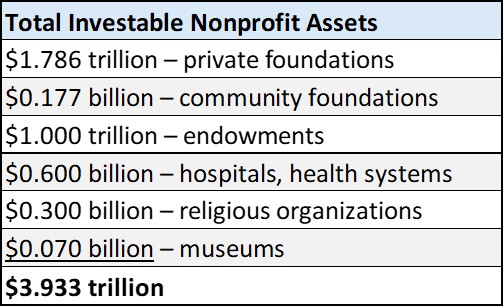
Looking back over the last four decades, the best time to pitch an outsourced OCIO proposition was probably about thirty years ago. Fewer competitors, better margins, plenty of prospects. But there’s still runway ahead for the go-getters. Here’s a rough estimate of total investable assets for the nonprofit, non-pension market:
The corporate defined benefit business is a land unto its own, actuarial, regulated, and liability driven, with a focus on funding levels and cost reduction. Better to let Marsh, Goldman, Blackrock, et al., deal with those headaches.
New business for most OCIOs will come from private wealth and related foundations, a booming market. But when it comes to the moneyed class it’s all about service.
Speaking of service
A sizable southern foundation called a few weeks ago to discuss their OCIO’s poor service. Didn’t matter that the 10-year investment performance was excellent – our data put them in the top third. According to the board their OCIO responds late to their requests and pays lip service to their concerns. They were here to talk about a change.
When families are asked what qualities are most important in a client service advisor, trust and responsiveness top the list. And yet, after twenty years working with OCIOs – recruiting, consulting, M&A, this directory – poor service and communication is today’s number one complaint.
Maybe it’s turnover and the lamentable loss of passion and focus. Once a founder sells it’s hard to sustain that intensity and vision. Most OCIO trailblazers have been in business for thirty to forty years, some longer, and many are aging out.
Unless an OCIO is family-owned like Hirtle & Co. with succession in place, or that rare private partnership with a two-hundred-year-old history like Brown Brothers Harriman, merging is usually inevitable.
With heady valuations, it’s hard to say no to a generous offer. In the last few years, Hall Capital, NEPC, Agility, Truvvo, Ellwood Associates, New Providence, CornerStone, PFM, and Permit Capital, among others, have snuggled up to big money patrons.
Mr. Hirtle, industry doyen and long-standing client, describes the challenge this way:
Over the past decade and more, markets have been so consistently productive that almost everyone is capturing historically strong returns. So, differentiation in our business depends on exceptional professional service.
Daniel Kahneman famously differentiated the perfectly rational humanoid “econs” of the economic textbooks – who only care about performance – from real people with real everyday emotions, pressures, and concerns which he called “humans”.
Exemplary service means focusing on our clients’ success and well-being, those human elements Professor Kahneman describes. Our mission is to ease their minds and help keep their commitments. We never want to disappoint them. That means both strong performance and great client care.
—Charles Skorina
(download PDF directory only)
(down PDF newsletter & directory)
NEWS AND COMMENTARY
ABOUT
Tarek Saghir, new CIO, UC Berkeley Endowment IMC
x CIO Brandeis U, GroveStreet, CPPIB, McKinsey, BS Chem Eng, U Toronto, MBA & J.D. Harvard

Adela Skenderasi, new CIO, Cystic Fibrosis Foundation

Brendon Reay, new MD investments Bush Foundation
Mark L. Baumgartner, new CEO/CIO University of Florida Investment Corp
SKORINA IN THE NEWS
2-19-25 Institutional Investor: Most endowment returns aren’t high enough to cover universities’ costs
11-15-24 Institutional Investor: Nokia taps mercer to navigate evolving corporate pensions
5-7-21 BloombergNews: Yale Names Alex Banker Interim Endowment Chief, Plans Search
5-6-21 The New York Times: David Swensen, Who Revolutionized Endowment Investing, Dies at 67
5-6-21 Forbes: Yale Endowment Chief David Swensen Leaves Legacy of Top College Investment Leaders
CHARLES A. SKORINA & COMPANY works with leaders of Endowments, Foundations, and Institutional Asset Managers to recruit Board Members, Executives Officers, Chief Investment Officers and Fund Managers.
Mr. Skorina also publishes THE SKORINA LETTER, a widely-read professional publication providing news, research and analysis on institutional asset managers and tax-exempt funds.
Our Practice:
• We recruit Board Members and Executive Officers, Chief Investment Officers and Senior Asset Managers.
• Our research and analytics are backed by over thirty years of hands-on recruiting experience and an unrivaled personal network.
• We collect performance, compensation, and background data on most senior institutional investment professionals in the U.S. and the funds they manage. We analyze that data to construct profiles of those managers and their funds, identify best-in-class people, and map their career trajectories.
• We share our research and insights in a widely-read professional newsletter – THE SKORINA LETTER – and website – www.charlesskorina.com.
• The New York Times, Wall Street Journal, Bloomberg, Thompson Reuters, Financial Times (Fundfire), Institutional Investor, Pensions & Investments, Private Equity International, and the institutional investment community use our research and analysis. Skorina has been interviewed on chief investment officer compensation issues on Bloomberg TV.
• Our work is regularly re-printed in Allaboutalpha.com and other industry magazines, blogs, and third- party web postings.
• We focus specifically and effectively on the world we know: Board members and Executive Officers, Chief Investment Officers, and Senior Asset Managers at institutional investment firms and funds – including sovereign wealth funds, endowments, foundations, pension funds, banks, investment banks, outsourced chief investment officer firms (OCIO), and sell-side money managers.
Prior to founding CASCo, Mr. Skorina worked for JP MorganChase in New York City and Chicago and for Ernst & Young in Washington, D.C.
Mr. Skorina graduated from Culver Academies, attended Michigan State University and The Middlebury Institute of International Studies at Monterey where he graduated with a BA, and earned a MBA in Finance from the University of Chicago. He served in the US Army as a Russian Linguist stationed in Japan.
Charles A. Skorina & Co. is based in Tucson, Arizona.
If it were easy . . .
It takes character to sit with all that cash and to do nothing —Charlie Munger
Jason Zweig – columnist, The Intelligent Investor, WSJ – wrestled recently with one of life’s enduring puzzles. Why do investors so often fall for the myth of the “dazzling investor” and lure of easy money?
Smart, savvy financiers took heady fliers on the media’s latest shooting star, twenty-four year old wunderkind Leopold Aschenbrenner, for example, and so far it’s been a white-knuckle ride.
Investment talent can come from the strangest places, we know, we’ve recruited some zingers over the years. But unless these oracles have had a few hard knocks along the way, they too often believe that this time really is different.
Sooner or later, however, a pesky bear market or related catastrophe gets in the way. Or as Viktor Chernomyrdin, a former Russian Prime Minister once put it, “The thing that never happens just happened again.”
Here’s a chart on past market declines and eventual recoveries.
Link: Market Declines: a History of Recoveries, MFS Investment Management
Even Berkshire Hathaway, with a compounded annual gain of 19.9%, nearly double the S&P 500′s 10.4%, “has had 10 negative return years, four years where it has fallen greater than -20% and six years where it underperformed the S&P500 by more than -20%.”
In Charlie Munger’s final interview he was asked an interesting question. If he and Warren Buffett were in their thirties starting over again today, did he think they could match their past investment success over the next sixty years? He answered this way. They were very intelligent, they worked very hard, and they were very lucky. But could they do it again? Probably not.
How many times in anyone’s life is a person given the opportunity to check all three boxes, he mused. Mr. Buffett, half tongue-in-cheek, once suggested another reason in Berkshire Hathaway’s 2022 Annual Report, “And, yes, it helps to start early and live into your 90s as well.”
The right stuff
As an analyst at Chemical Bank, back during the Mesozoic era, one of my assignments was to follow our Chicago based trading clients. As I soon learned, staying on top of any trader’s book was tough enough. But ascertaining their talent, discipline, and durability was exponentially more challenging. I pored over track records, history, context – statistics not stories, to rephrase psychologist Daniel Kahneman – and still wondered how the best ones did it.
Mr. Zweig’s colleague at the WSJ, Spencer Jakab points out that it can take years, even decades to judge the good from the lucky. (Paradox of Skill, Brad Steiman, DFA). Aschenbrenner’s sole claim to fame was a 165-page essay titled “Situational Awareness: The Decade Ahead,” a paper he wrote in his early twenties.
Markets and economies eventually recover as do great investors like Warren and Charlie — the ones with patience and discipline. We’ll see what Mr. Aschenbrenner learns from his debacle. He’s still in business managing an estimated $10 billion in assets.
In the end, Charlie’s right, it does indeed come down to character, along with brains, grit, and a little luck. As our go-to OCIO maven Jon Hirtle remarks time and again, “serious investors care deeply about keeping their promises.” We couldn’t agree more.
—Charles Skorina
Read More »